Better Compensation & Pricing
NEXA says that even at $2 billion in annual production, UMortgage couldn’t independently match NEXA’s pricing. NEXA credits the collective production of roughly 4,000 loan officers for its leverage with lenders.
Greenlight Mortgage · empowered by NEXA Lending’s platform
That’s how NEXA describes its platform. I’m Kenneth “KT” Travis, and Greenlight Mortgage is how I’m building on it.
If you’re a retail loan officer, a retail branch manager, a broker owner or a team leader, this page walks through how the NEXA platform works: compensation, Revenue Share, servicing, FSBO.com, the BDM Program and support. Then we put your real numbers next to it.
Rather talk first? Call KT at 903-918-9959 or email ktravis@glmtg.com.
Platform figures as published by NEXA Lending (thenexadifference.com, October 2026). They describe NEXA’s platform, not Greenlight Mortgage on its own.
KT’s Story
Personal background. No endorsement by the U.S. Marine Corps or Guinness World Records is implied.
I’m Kenneth Travis, better known as KT. I’m an eight-year Marine Corps veteran, former sergeant, and Guinness World Record holder in planking.
The preparation, discipline, and mental toughness it took to earn that record are the same qualities I bring to building a business.
I’ve spent roughly 14 years in the broker channel and ten years in retail. I’ve built businesses, led teams, and made expensive mistakes. My perspective comes from living this business.
I entered the mortgage industry working for a broker as an individual loan originator. The advice was, “Fake it till you make it.”
My Marine Corps training told me to build a plan and execute it. I became the top-producing originator in that office.
A partnership that proved costly taught me an early lesson about who you build with and how the business is structured. I eventually opened my own brokerage and grew it to 49 employees.
We had real success. We also had clunky technology, manual processes, and too much work holding everything together.
As the industry changed after Dodd-Frank, retail’s message became convincing: better technology, better systems, better support—and warnings about what you supposedly couldn’t do as a broker.
I bought in. I drank the Kool-Aid.
And I succeeded there, too. I became a number-one producer. My team closed approximately $200 million a year, and I earned seven figures.
Then margins tightened, and I started questioning what I was seeing.
Loan officers and retail branch managers were the backbone of the business. They generated the relationships, earned the trust, and brought in the revenue. Yet I felt too much of the pressure to protect company profits was falling on them.
I believe leadership should share that pressure with the people doing the work. I wasn’t seeing enough of that.
It changed what I was willing to build my future around.
I returned to the broker community and hit reset.
For three years, I studied how brokerages operated. Compensation. Expenses. Technology. Support. Branding. What it actually takes to grow.
I compared models, challenged assumptions, and kept measuring.
Eventually, I found a model I believed could be the answer—a third option that brought together more of what I wanted. I studied it deeply and committed to that direction.
Then NEXA Lending gave me a reason to look again.
The more I studied it, the stronger the case became. I had to be willing to reconsider a conclusion I had already reached.
NEXA is the strongest platform I’ve found in this industry—wholesale or retail.
It brings together the wholesale options I value, the infrastructure I need to grow, and the ability to build Greenlight Mortgage under its own brand and voice.
I see a model that gives originators and leaders more control over what they build, with support behind them and more ways to serve their borrowers.
That combination matters.
I want the loan officer to keep more of what they earn. I want the borrower to receive a better deal. I want the business to create more opportunity for the families depending on it.
And when retail mortgage companies say, “You have to sell your value,” my question is simple:
Why shouldn’t that value include a better deal?
Great service and competitive pricing belong together. So do ambition, strong earnings, and having a life outside your production report.
That’s what I’m building toward with Greenlight Mortgage empowered by NEXA Lending’s platform.
I understand skepticism. If something sounds too good to be true, examine it.
Bring your numbers. Bring your questions. Compare what you actually keep after expenses, the support you receive, the options available to your borrowers, and the time it takes to operate your business.
Whether you’re a retail loan officer, a branch manager, or a broker owner, give the comparison an honest look.
Then ask yourself the question I had to face:
Am I choosing the best path forward—or defending a decision I already made?
Pride and ego can make it hard to reconsider something you’ve spent years building. I understand that, too.
But if the numbers reveal a better opportunity, what would refusing to consider it cost you?
If your comparison showed a path to twice the take-home income—or the same income with half the closings—what could that make possible?
More of your children’s games. More time with your spouse or partner. The space to take care of your health, strengthen your finances, and build something your family benefits from.
More money to build a legacy. More time to be part of it.
My experience brought me to this conviction. Your business deserves the same careful examination.
You’ve seen why I chose this path. Now take a closer look at what it could make possible for your business—and your life.
The Proof · as told by NEXA
This one isn’t my story, and it isn’t Greenlight’s production. It’s a case NEXA tells on its own site. According to NEXA’s published account, UMortgage, a brokerage it describes as producing about $2 billion a year with 256 loan officers, closed its independent brokerage operation and moved to the NEXA Lending platform. NEXA lists four reasons UMortgage’s CEO, Anthony Casa, gave for the move.
NEXA says that even at $2 billion in annual production, UMortgage couldn’t independently match NEXA’s pricing. NEXA credits the collective production of roughly 4,000 loan officers for its leverage with lenders.
UMortgage’s former model couldn’t offer loan officers 100% compensation. NEXA says its annual volume lets it give back to loan officers: the more NEXA funds, the more its loan officers receive in return.
Even at that size, UMortgage couldn’t share its profits with the people helping it grow. NEXA’s Revenue Share model rewards loan officers for contributing to the company’s expansion.
NEXA calls this the final deciding factor: loan officers can participate in servicing income, keep visibility into their client portfolios, and keep serving those clients after closing.
Source: NEXA Lending, thenexadifference.com (captured October 2026). NEXA’s August 24, 2026 announcement describes the UMortgage acquisition and more than $2 billion in added annual volume. Loan-officer count as reported on NEXA’s page.
If you own a brokerage, you already know where the hours go: compliance processes, audits, call reports, payroll, and the operational work that never generates a loan. NEXA’s platform is built to carry much of that administrative load, so you can keep building your own business under your own brand.
Your personal licensing, legal and professional obligations stay yours. The platform supports the operations around them.
Compensation
NEXA’s line is “payday is every day.” Here’s the actual sequence it describes: your loan closes, NEXA receives the funds, you submit your payroll, and your compensation is processed. No waiting two weeks or a month for a company payroll cycle. It doesn’t mean cash at the closing table; it means the payroll step is in your hands once the funds arrive.
NEXA describes its compensation in layers, all designed around what the originating loan officer takes home. I’ll walk through them in the order they actually apply.
NEXA’s program description says no built-in company margin is added to lender pricing. You see raw pricing, which lets you offer your borrowers the most competitive options available to you.
When you close through NEXA’s correspondent channel, NEXA says you can view the actual purchase advice, so you can see what NEXA earned on the transaction.
That’s pricing transparency. It’s separate from the operational cost and Revenue Share allocation below, and it isn’t a promise that any given rate beats every other lender.
Every loan carries a 25 basis point (BPS) operational cost, calculated on the loan amount.
Of the revenue that remains after the 25 BPS, 12% is held for NEXA’s Revenue Share model.
The compensation values on the plan sheet below already have both deductions built in. Don’t subtract them a second time.
Take the 300 BPS margin row. Subtract the 25 BPS operational cost: 275 BPS remain. 12% of 275 is 33 BPS for Revenue Share. 275 − 33 = 242 BPS, which is exactly what the chart shows in the compensation column. Every row follows the same order.
Arithmetic of NEXA’s published base structure, shown so you can check the chart. Not a quote for any specific loan.
No volume requirement. No recruiting requirement.
As NEXA presents it, when you fund an eligible loan through its correspondent channel with a designated lender, you receive 100% of the commission check. NEXA’s program text names UWM, PennyMac, Longbridge, Finance of America and Deephaven; the plan sheet shows the designated-lender logos in effect for the plan. Confirm the current list before you count on a lender.
The 25 BPS and 12% on those loans are credited to your Growth & Marketing Ledger: a fund for qualifying business expenses like a CRM, advertising, Realtor lunches and networking events. You upload receipts and NEXA reimburses approved expenses under the program’s rules.
Grow the platform, earn 100% on correspondent loans.
With NEXA’s correspondent lenders, NEXA says you can qualify for 100% commission by helping NEXA grow, through recruiting an originator who funds loans. NEXA’s page and its plan sheet describe the recruiting cadence differently, so I’ll walk you through the current written qualification before you rely on it.
As with Unlimited, the 25 BPS and 12% go into your Growth & Marketing Ledger for business and operating expenses.
Gross revenue, cash compensation, ledger credits and reimbursements are four different things. Ledger credits reimburse approved business expenses with receipts. They are not unrestricted take-home pay, and the Freedom Equation keeps them in their own column.
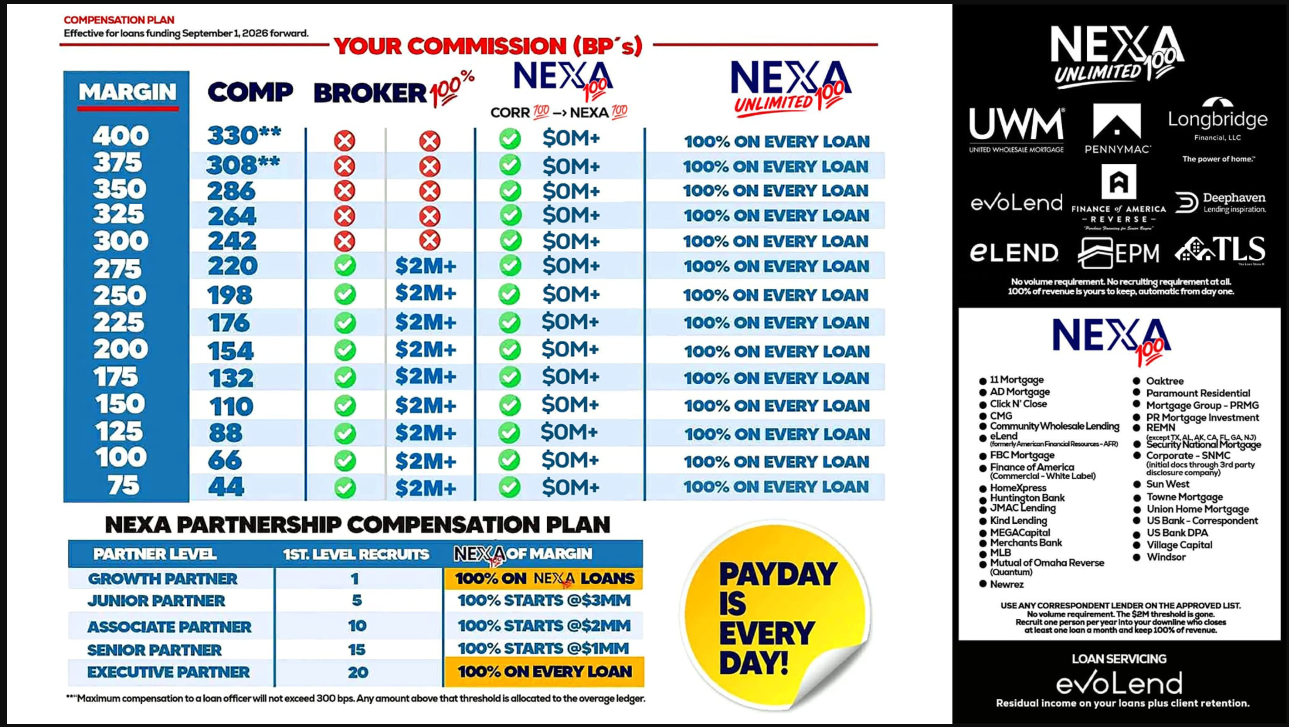
| Margin (BPS) | Compensation shown on chart (BPS) | Broker 100 | Broker 100 volume label | NEXA 100 (correspondent) | NEXA 100 volume label | NEXA Unlimited 100 |
|---|---|---|---|---|---|---|
| 400 | 330** | ✕ | ✕ | ✓ | $0M+ | 100% on every loan |
| 375 | 308** | ✕ | ✕ | ✓ | $0M+ | 100% on every loan |
| 350 | 286 | ✕ | ✕ | ✓ | $0M+ | 100% on every loan |
| 325 | 264 | ✕ | ✕ | ✓ | $0M+ | 100% on every loan |
| 300 | 242 | ✕ | ✕ | ✓ | $0M+ | 100% on every loan |
| 275 | 220 | ✓ | $2M+ | ✓ | $0M+ | 100% on every loan |
| 250 | 198 | ✓ | $2M+ | ✓ | $0M+ | 100% on every loan |
| 225 | 176 | ✓ | $2M+ | ✓ | $0M+ | 100% on every loan |
| 200 | 154 | ✓ | $2M+ | ✓ | $0M+ | 100% on every loan |
| 175 | 132 | ✓ | $2M+ | ✓ | $0M+ | 100% on every loan |
| 150 | 110 | ✓ | $2M+ | ✓ | $0M+ | 100% on every loan |
| 125 | 88 | ✓ | $2M+ | ✓ | $0M+ | 100% on every loan |
| 100 | 66 | ✓ | $2M+ | ✓ | $0M+ | 100% on every loan |
| 75 | 44 | ✓ | $2M+ | ✓ | $0M+ | 100% on every loan |
✓ / ✕ are the chart’s positive and negative indicators. ** Maximum compensation to a loan officer will not exceed 300 BPS; any amount above that threshold is allocated to the overage ledger. The 330 and 308 cells are not cash compensation above the cap. The chart does not state a measurement period for the $2M+ label.
| Partner level | 1st-level recruits | NEXA 100 of margin (as shown on chart) |
|---|---|---|
| Growth Partner | 1 | 100% on NEXA 100 loans |
| Junior Partner | 5 | 100% starts at $3MM |
| Associate Partner | 10 | 100% starts at $2MM |
| Senior Partner | 15 | 100% starts at $1MM |
| Executive Partner | 20 | 100% on every loan |
Printed on the sheet: “No volume requirement. No recruiting requirement at all. 100% of revenue is yours to keep, automatic from day one.”
Printed on the sheet: “Use any correspondent lender on the approved list. No volume requirement. The $2M threshold is gone. Recruit one person per year into your downline who closes at least one loan a month and keep 100% of revenue.”
Loan servicing: evoLend. Residual income on your loans plus client retention. Also on the sheet: “Payday is every day!” badge.
Lender lists are historical chart content as of the plan’s effective date, not a current eligibility guarantee.
Executive Partner
NEXA describes recruiting as how you build long-term income, influence and a legacy on the platform. The benefits below belong to Executive Partner status, the top tier of NEXA’s partnership plan (20 first-level recruits on the plan sheet). They are not entry-level benefits for every loan officer.
The potential for seven-figure annual Revenue Share income without personally funding a loan. That’s a ceiling NEXA describes for this tier, not what a typical recruit or new originator earns.
100% compensation on every loan you personally fund, regardless of the lender used or the number of loans you fund, under the applicable plan.
NEXA says it covers the cost of premium health benefits for Executive Partners and provides access to NEXA’s doctor.
Participation in leadership meetings that inform NEXA’s growth and direction.
A personalized rocking chair placed on the porch of Midnight Ranch in Montana.
Additional recognition, access and partner privileges, as defined in NEXA’s current partner terms.
| Partner level | 1st-level recruits | NEXA 100 of margin (as shown) |
|---|---|---|
| Growth Partner | 1 | 100% on NEXA 100 loans |
| Junior Partner | 5 | 100% starts at $3MM |
| Associate Partner | 10 | 100% starts at $2MM |
| Senior Partner | 15 | 100% starts at $1MM |
| Executive Partner | 20 | 100% on every loan |
Transcribed from the plan sheet. Recruit definitions, measurement periods and other qualification terms are set by the current written plan. See the original plan sheet.
Benefits as presented on NEXA’s published materials, subject to current partner terms.
The Long View
NEXA reports that over an eight-year period, 12 members of the NEXA family passed away while working with the company, and that Revenue Share has continued to be paid to their families.
That’s NEXA’s history, as it tells it on its own site. It isn’t my family’s story, and it isn’t a survivor-benefit contract. But it shows what Revenue Share can be: income tied to something you built, not only to the loans you closed this month.
Source: NEXA Lending, thenexadifference.com (captured October 2026).
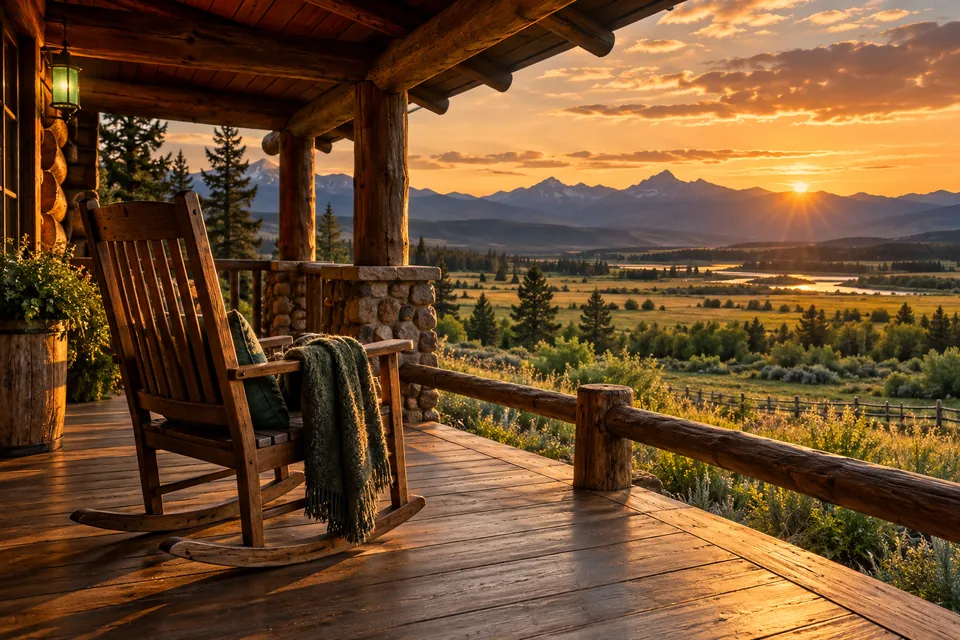
When you eventually stop originating, how do you replace production income? NEXA presents Revenue Share as a way to build income that can continue after you retire, as long as the loan officers in your downline remain with NEXA and keep producing. It isn’t guaranteed lifetime income, a pension or transferable equity. It depends on the people you helped bring in.
More money to build a legacy. More time to be part of it.
NEXA Plus
NEXA describes NEXA Plus as a second form of income for loan officers. Through evoLend, a third-party servicing company, you can see your clients’ servicing activity after closing: when they make a payment, and when they order a payoff.
An eligible loan closes through NEXA’s correspondent channel.
evoLend servicing gives you real-time visibility into that loan.
As NEXA describes it, when your borrowers make their monthly payments, you may receive a portion of the servicing income.
Servicing-related payments depend on eligibility, the correspondent channel, servicing arrangements and borrowers continuing to pay. Not every loan in every channel qualifies, and no payout rate or duration is guaranteed.
Program description from NEXA’s published materials (thenexadifference.com, October 2026).
FSBO.com
Imagine having direct access to for-sale-by-owner opportunities built right into your mortgage platform.
FSBO.com is one of the country’s largest platforms for homeowners selling without an agent. According to NEXA’s account, FSBO.com was acquired by NEXA founder Mike Kortas in 2026, and a dedicated Loan Officer Portal launched in April 2026 to connect NEXA originators with FSBO opportunities. FSBO.com isn’t owned by me or by Greenlight; it’s a platform tool available through NEXA.
Selling without representation means a homeowner manages all of this, alone:
When sellers recognize those challenges, a licensed loan originator can help with the financing questions and make a trusted Realtor introduction for everything else. You’re not their lawyer or their listing agent. You’re the professional who connects them with the right ones.
Engage sellers directly and identify purchase and financing opportunities.
Bring local agents real listing opportunities and build long-term referral partnerships.
Seller connections can lead to purchase loans, financing for the seller’s next home and repeat business.
NEXA runs weekly training on the portal, outreach strategy and Realtor introductions.
The strongest FSBO strategy isn’t just finding borrowers. It’s using seller connections to become valuable to the best Realtors in your market.
One seller relationship can open several doors. None of them are guaranteed, but each is a real opportunity:
Bring a local Realtor a real opportunity, not another referral request.
Financing for wherever the seller is moving next.
A financing opportunity on the other side of the sale.
One introduction can become a long-term professional relationship.
Repeat purchase and refinance opportunities down the road.
Ready to go deeper with a Realtor partner? That’s where the BDM Program comes in. See the BDM Program.
FSBO.com chronology and program details as described in NEXA’s published materials.
BDM Program
In a high-rate market, standing out matters. NEXA’s BDM Program gives your marketing partners a documented, employed way to market for you, under approved employment and compensation arrangements.
Professionals who regularly work with potential mortgage clients: Realtors, CPAs, attorneys and financial advisors. Per NEXA’s program description, a BDM can’t be licensed as an MLO, and the program excludes Arizona. Not everyone in those professions automatically qualifies.
Your marketing partner completes NEXA’s onboarding as a part-time W-2 employee.
They perform the qualifying marketing work. When it brings in a loan, you, the licensed loan officer, handle the origination from application to closing.
After payroll is submitted, NEXA pays the BDM through its payroll process from the transaction commission, under the approved arrangement.
NEXA lists four compensation structures for BDMs. The actual amounts and tiers are set in each approved individual arrangement.
A fixed dollar amount for a qualifying closed transaction.
The dollar amount changes at defined monthly closing tiers.
A defined basis-point (BPS) amount related to loan size.
The BPS amount changes at defined monthly closing tiers.
NEXA reports paying more than $500,000 to BDM marketing partners since February 2026. That’s a platform milestone, not a projection of what any one partner will earn.
BDM pay is compensation for documented marketing work under an approved employment arrangement. It is not a “send a referral, get paid” program. Current agreements, state eligibility and the program’s formal title are confirmed during onboarding.
Program description as published by NEXA (thenexadifference.com, October 2026).
Freedom & Support
On NEXA’s platform, you run your own business, and the decisions inside your files are yours to make within lender rules and applicable policies.
NEXA runs as a Zoom-based company. With an internet connection you can reach live support, lender rooms and operations teams. Where you can originate still depends on your licensing and location requirements.
You choose your processor. You choose your lender. You set the rate you offer. You handle pricing exceptions within the applicable policies. No middle manager standing between you and those decisions.
Payroll, HR, compliance, licensing and marketing help from a live team. NEXA publishes support coverage of 12 hours a day, plus 5 hours on Saturdays.
NEXA reports more than 30 lenders dedicating 12 hours a day in its Zoom lender rooms to help with scenarios, pricing questions and file issues, subject to current availability.
Support scope and hours as published by NEXA (thenexadifference.com, October 2026).
From KT
I didn’t build NEXA. I studied it for a long time, I tried to poke holes in it, and I changed my mind about a conclusion I’d already reached. What I’m building is Greenlight Mortgage on top of it.
Everything above is how the platform works on paper. Paper doesn’t tell you what it would mean for you. Your numbers do: what you produce, what you actually keep, what it costs you to run, and what you want your life to look like. So let’s look at those.
Read my answers to the top questions people ask before you decide.
What could the business you already generate make possible in a different model?
Request The Freedom Equation — Your Personalized Mortgage Business Comparison.
We’ll use your production, compensation, expenses, and business goals to compare your current model with Greenlight Mortgage empowered by NEXA Lending’s platform.
See how the numbers stack up, what support looks like, and what the differences could mean for the business—and life—you want to build.
We’ll email you a short questionnaire to gather the details needed for your personalized report. No obligation to make a move.
KT has been notified. The fastest way to get your Freedom Equation started is the short questionnaire, right now. We’ll also follow up by email.
Start the short questionnaire nowIf you need to reach KT sooner, call 903-918-9959 or email ktravis@glmtg.com.